Home: bestmedicalaid.co.za
Finest Gap/Top Up Plan for medical claim shortfalls.
All the benefits and costs.
Join the Best Gap/Top up Insurance Plan
Finest Gap/Top-Up Cover in South Africa: Gap cover is an FSCA-regulated insurance product that protects medical scheme members from out-of-pocket costs when specialists charge above scheme tariffs. It covers in-hospital shortfalls (up to 500% of tariff), co-payments, non-DSP penalties, and sub-limits. Available nationwide for all registered medical aid members, with premiums from R293/month for individuals.
- Who: Members of registered South African medical schemes
- What: Supplementary cover for specialist shortfalls & co-payments
- Why: Prevents tens of thousands in unexpected medical bills
- Where/When: Online, 24/7, across South Africa

Why Zestlife Gap Cover 2027 Could Save You Thousands on Medical Bills!
What will happen when your medical aid does not pay your treatment in full?Medical schemes have experienced declining membership, driven largely by younger members delaying their entry into medical schemes and increasing affordability pressures.
In response, medical schemes have sought to contain premium increases by reducing certain benefit limits and introducing or increasing co-payments, which ultimately shifts a greater portion of the healthcare funding liability to you.
The difference between what medical schemes cover and what private practitioners charge frequently amount to shortfalls of tens of thousands of Rands, for which the you are liable.
The Zestlife Gap Cover takes care of these unforeseen medical expenses and helps patients focus on recovery.
It works with all South African medical schemes and has no entry age limits.
It is a smart choice for many medical aid members and no one should be without one!
What Is the Difference Between Medical Aid and Gap Cover?

The key difference is simple.
Medical aid covers your core health care costs while GAP cover pays the shortfall when your medical aid does not cover the full medical treatment costs.
What Does Medical Aid Cover?
Medical aid helps pay for:- hospitalization
- Doctor and specialist consultations
- Prescribed treatments and medication
Many medical aid members are caught by medical claim shortfalls like specialists charging 200% to 500% of scheme rates, procedures that require co-payments, and plans that have limits or exclusions.
These gaps can lead to unexpected medical bills, especially during emergencies.
As an example, a heart procedure might cost R100,000, but your medical aid only pays R60,000.
Gap cover should pay the R40,000 shortfall.
What Does GAP Insurance cover?
Gap Cover is a supplementary insurance product that helps cover the difference between what your medical aid pays and what your healthcare provider actually charges. It helps reduce your financial risk during hospitalisation and specialist treatments.Depending upon the plan you join gap cover may include:
- Specialist shortfalls
- In- hospital cost gaps
- Certain Co-payments.
- Once off payment benefits on diagnosis of a health event.
It pays that gap for in-hospital care and several out-patient treatments.
Do you need both medical aid and gap cover?
Yes if you want to avoid unexpected costs, because having both means less risk of large medical bills, better financial protection during emergencies and greater peace of mind knowing you can afford the finest treatment.Medical Aid gets you treated and Gap Cover helps you afford that bill.
They are designed to work together and not to replace each other.
The Zest Gap cover plan differs from other gap plans in key ways:
- Some competitors limit cover to certain ages, whereas Zestlife has no max entry or expiry age.
- Others might exclude family options, but Zestlife offers plans for individuals and families.
- Some may provide good cover, but have higher waiting periods or fewer extras. Zestlife has no general or condition-specific waiting periods.
- Zestlife includes oncology support and travel cover abroad, ideal for people who travel.
- It covers robotic procedures, which are more common.
Many plans miss this. - The Universal plan offers a member on a 100% medical scheme plan cover up to 6 times tariff and a on a 200% plan cover up to 7 times tariff.
- Zestlife pride themselves on fast claim payments, often within days with Reddit users giving Zest good reports.
Key Benefits of Zestlife Gap Cover 2027:
- Shortfalls for consultation fees charged by an admitting GP prior to and following in-hospital surgery.
- Benefits are also payable in the event of shortfalls and/or co-payments arising from certain out-patient procedures. including CT, PET and MRI scans.
- Co-payments for hospital admissions, CT, PET and MRI scans and specified medical procedures.
- Co-payments when treated in a non-network hospital or by a non-network medical practitioner.
- MRI, PET and CT Scans in excess of medical scheme sub-limits
- Co-payments when the annual cancer treatment limit is exceeded.
- Treatment in a hospital casualty facility or by a GP where there is no registered hospital casualty facility within a 30km radius, within 48 hours following accidental injury.
- First night home recovery benefit pays the difference between the costs charged for support services such as a nurse or carer, for the first night at home following surgery in a hospital’s operating theatre.
- Neonatal intensive care unit benefit is paid paid towards the costs if a newborn is admitted to NICU care for 3 or more consecutive days.
- Child development screening benefit covers the Medical Specialist costs for developmental screenings including ADHD, speech impairment, dyslexia and autism assessments, for children younger than 11.
- Medical scheme upgrade contribution waiver benefit pays out when a medical scheme approves an option upgrade outside the normal medical scheme option upgrade window due to a medical diagnosis.
This benefit will pay an amount equal to the increase in the premium due to the upgrade from the date of the upgrade to the end of the calendar year. - Medical expense shortfalls and co-payments on internal prosthesis (including artificial joints).
- Cosmetic Breast Reconstruction of a non-affected breast.
Extra features added value:
- Zestlife Gap Cover provides cover for cancer treatment shortfalls, co-payments and limit excesses as well as a diagnosis benefit and optional extended cancer cover.
- Extended Cancer Cover pays you or any of your dependents insured under the policy are diagnosed with cancer for the first time.
- Accidental tooth fracture benefit Unexpected costs (including medical aid and gap cover premiums arising from accidental death or accidental permanent and total disability.
- Once off payment for death or permanent total disability arising from violent crime.

Choosing Your Plan
Zestlife offers 3 main plans for 2027, Optimal, Essential, and Universal. Each plan is designed for different member needs.
- Universal Plan: offers the most comprehensive medical expense shortfall cover with extensive financial protection against a wide range of health risks.
- Essential Plan: offers affordable cover for the most frequent medical expense shortfalls, and additional financial protection for selected health risks
- Optimal Plan: offers high levels of cover and affordability to match the needs of single individuals and families younger than 42.Younger members may question the need for Gap Cover alongside their medical aid.
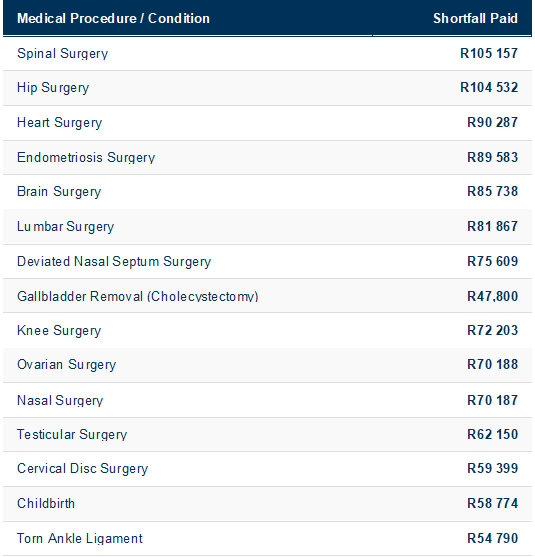
The reality is simple: Medical aid shortfalls are real and can be significant as the need for medical treatment can arise unexpectedly at any age.Here are thetop 15 claims paid to members under the age of 42
Unique Policy Benefit
There are NO general waiting periods or condition specific waiting periods that withhold cover after the commencement date of the policy!Claim pay-outs are either made to you or directly to the treating doctors, specialists or medical service providers, at your discretion.
What Gap Cover Doesn't Include
Gap plans do not cover day-to-day medical expenses.
If your medical aid would have never covered a specific claim, the gap plan will not provide benefits either.
If you have medical aid, you should have Gap Cover to complement it.
It is your best solution to protect you from in-hospital medical aid claim shortfalls.
Frequently Asked Questions: What is the Finest Gap Cover Plan?
What is the biggest risk if I don't have Gap Cover?
Without Gap Cover, you may face unexpected out-of-pocket expenses due to in-hospital claim shortfalls or procedure co-payments. Medical aids often don't fully cover these costs. A Gap plan will ensure those shortfalls are paid.
How does Gap Cover protect me financially?
Gap Cover is a safety net, paying the difference between what your medical aid pays and the actual cost of your treatment, helping to prevent unexpected medical debt.
Why should I consider Gap Cover if I have an expensive medical aid plan?
Even higher-cost, comprehensive plans only cover up to 200% of medical aid rates. Private providers can charge up to 500% of these rates. That can leave you with significant in hospital shortfalls.
Does Gap Cover have any waiting periods?
No, Zestlife Gap Cover has no general or condition-specific waiting periods. However, there is a 12-month waiting period for medical conditions that have had medical advice, a diagnosis, or treatment received or that would reasonably have been recommended for a year before the policy start.
Can Gap Cover assist with cancer-related costs?
Yes, an Extended Cancer Cover provides up to R264,000 for first-time cancer diagnoses, easing the financial burden of treatment.
What out-of-hospital procedures are covered?
Benefits are also payable in the event of shortfalls and/or co-payments arising from certain out-patient treatment and procedures. There are 60 procedures that are frequently performed out-of-hosptial for which shortfalls are covered such as skin grafts, laser eye surgery, grommets and chemotherapy. Please contact us for the full list.
Get Your Free Quote
Talk to me — I am here to help you, at no charge.
Send me your questions and concerns. I'll answer them for you.
The plan works with any medical aid!
Enhance your cover without having to change from your medical scheme!
Note: Benefits are plan dependant. It is important to note that this product is specifically designed to help you meet the private tariffs charged by doctors, anaesthetists, radiologists, physiotherapists and specialist surgeons, for in-patient treatment. It does not cover the actual cost of the hospitalisation.
No benefits are payable for a period of 12 months from the start date of cover in respect of medical conditions, for which in the 12 months before the start date of the cover, medical advice, diagnosis, care or treatment was received or would reasonably have been recommended. Pregnancy before the start date of cover will be regarded as a pre-existing condition and any pregnancy and birth related claims will be excluded for 12 months from the start date of the cover.
Terms and conditions do apply.
You must consult the schemes/company product brochures and rules for comprehensive benefit descriptions.
We will offer you the best help at no cost!
Easy-to-understand articles on medical aid.
 083 655 2164
 Medical aid pays healthcare costs.
What if a disability stops your income?
Trust isn't something you claim. It's something you earn

Peter Pyburn - Authorised Financial Services Provider has been fully licensed to provide expert financial services since 1991.
Based in Sandton, Johannesburg, Gauteng, we specialise in comprehensive financial planning including: Death and Disability Cover, Retirement Planning, Investment Strategies, Medical Aid, Estate Planning.
FSP Licence 2995 and Medical Aid Accreditation BR 7428.
Why Choose Peter Pyburn?
- ✔ FSCA Registered Financial Services Provider
- ✔ Over 3 decades of hands-on experience
- ✔ Independent advice across multiple schemes like Discovery, Momentum, Bonitas, Fedhealth, Genesis, CompCare and Medshield.
- ✔ Focused on your long-term outcomes
- ✔ No Broker fee as the medical aid pay us.

Council of Medical Schemes
Medical Disclosure
By submitting an enquiry you agree to us collecting the information in the fields above. Please refer to our POPI Manual.
Your data will be processed according to the Protection of Personal Information Act (POPIA) guidelines.
Important Disclaimer: This content is for informational purposes only and does not constitute financial or healthcare advice.
Medical aid benefits are subject to change.
Please consult the medical aid brochure and speak to bestmedicalaid.co.za before making any decisions.
South African rights reserved.
By Peter Pyburn | CMS Broker Accreditation: BR 7428 | FSP Licence: #2995 (Licensed since 1991)
Regulated by the Council for Medical Schemes (CMS)
This webpage is for informational purposes only and does not constitute financial or medical advice.
Contact bestmedicalaid.co.za for qualified for advice specific to your situation.